What is the market overview and definition of the Warehouse Robotics Fleet Orchestration Market?
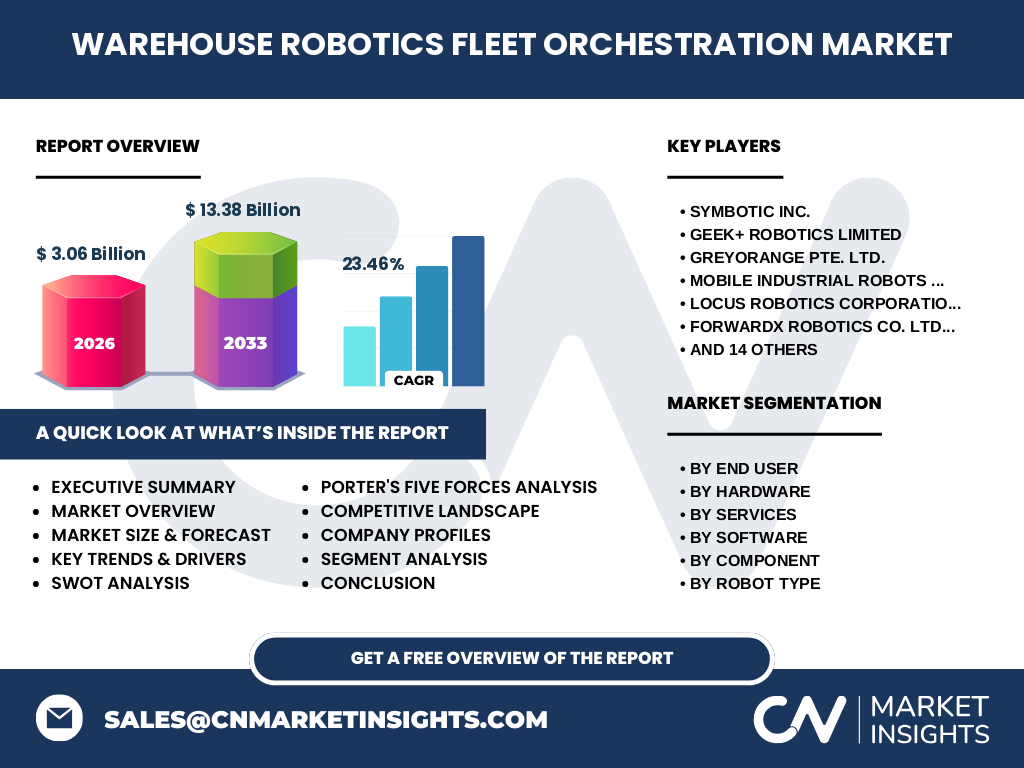
The Warehouse Robotics Fleet Orchestration Market encompasses software, hardware, and services designed to coordinate multi-vendor automated guided vehicles and autonomous mobile robots. Our analysis values the Warehouse Robotics Fleet Orchestration Market market size at $3.06 Billion in 2026, driven by complex supply chain demands across major logistical hubs.
What are the key market drivers, restraints, challenges, and opportunities shaping the Warehouse Robotics Fleet Orchestration Market?
Labor shortages in major distribution centers serve as primary Warehouse Robotics Fleet Orchestration Market industry trends, pushing adoption higher. However, integration complexities with legacy Warehouse Management Systems pose severe constraints. Opportunities abound in edge-computing architectures that reduce latency for high-speed sorting applications.
The Shift Toward Heterogeneous Fleet Management
Industry players increasingly demand interoperability between distinct robot types like Automated Guided Vehicles and Autonomous Mobile Robots. This structural shift benefits orchestration platforms that utilize VDA 5050 standards to unify disparate hardware from suppliers such as Mobile Industrial Robots (MiR) A/S and Geek+ Robotics Limited.
How did the COVID-19 pandemic impact the Warehouse Robotics Fleet Orchestration Market and shape its recovery?
The pandemic exposed severe vulnerabilities in manual fulfillment operations, accelerating automation budgets globally. Post-pandemic recovery trajectories show enterprises prioritizing scalable, cloud-based fleet software to manage sudden volume surges without increasing physical footprint.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features a mix of specialized software providers like InOrbit Inc. and Formant Inc. alongside hardware-software integrated giants like Symbotic Inc. and Locus Robotics Corporation. Market concentration is intensifying as leading vendors acquire niche navigation mapping startups to secure end-to-end capabilities.
Executive Summary of the Warehouse Robotics Fleet Orchestration Market
Our comprehensive Warehouse Robotics Fleet Orchestration Market analysis reveals a high-growth sector set to expand rapidly. Driven by soaring e-commerce volumes and labor constraints, the ecosystem requires strategic investments in multi-agent path finding algorithms and robust cybersecurity protocols.
Market Forecast and Growth Projections
Our forecast models project the market to expand from $3.06 Billion in 2026 to $13.38 Billion by 2033. This trajectory represents a robust 23.46% CAGR, fueled by rapid deployments across pharmaceuticals, automotive manufacturing, and high-density retail fulfillment centers.
Detailed Segmentation Analysis of the Warehouse Robotics Fleet Orchestration Market
Segmentation spans across end users, hardware, services, software, components, robot types, applications, and deployment modes. Fleet Management Software and Autonomous Mobile Robots lead demand, serving critical roles in optimizing inventory management and accelerating order fulfillment cycles.
Geographic Distribution and Regional Performance
North America dominates adoption due to advanced e-commerce infrastructure and high labor costs, while Europe follows closely driven by strict occupational safety regulations. Asia-Pacific emerges as the fastest-growing region, powered by booming manufacturing hubs in China, Japan, and South Korea.
In-Depth Regional Review and Logistical Constraints
Regional performance hinges on local labor laws, wireless spectrum availability, and facility real estate costs. In densely populated European urban logistics centers, high land costs favor multi-tier vertical storage managed by sophisticated orchestration software rather than sprawling horizontal footprints.
Strategic Positioning of Leading Companies
Market leaders employ distinct strategies: GreyOrange Pte. Ltd. focuses on AI-driven fulfillment execution, Locus Robotics Corporation excels in collaborative retail picking, and BlueBotics SA provides robust navigation middleware. These positions dictate their dominance across different industrial verticals.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of buyers remains moderate due to high switching costs associated with proprietary robotics software. Threat of new entrants is mitigated by steep R&D requirements in multi-agent path finding, while rivalry among established platform providers intensifies price competition.
SWOT Analysis of the Warehouse Robotics Fleet Orchestration Ecosystem
Strengths lie in advanced AI routing and seamless hardware integration capabilities. Weaknesses involve high initial capital expenditure. Opportunities emerge in predictive maintenance integrations, whereas threats include potential cybersecurity vulnerabilities in cloud-connected warehouse automation networks.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with semiconductor and sensor raw material suppliers, flows through hardware manufacturers and software developers, and culminates in system integrators deploying solutions for end-users like global logistics providers and pharmaceutical distributors.
Investment Insights and High-Potential Areas
High-potential investment areas center around Edge and Hybrid deployment modes that ensure uninterrupted operations during network outages. Venture capitalists and strategic buyers should target startups specializing in cross-vendor interoperability and advanced task scheduling algorithms.
Conclusion and Strategic Takeaways
The Warehouse Robotics Fleet Orchestration Market represents a critical investment frontier in modern logistics. Achieving market leadership requires balancing proprietary hardware ecosystems with open software standards to capture growing demand across electronic commerce and retail sectors.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining trade registry data, primary executive interviews with supply chain directors across North America and Europe, and secondary macroeconomic indicators regarding manufacturing output and automation spending.
Scope of the Report and Coverage Parameters
This report covers global deployment trends, component-level breakdowns, and vendor market shares from 2026 through 2033. Limitations exclude small-scale, non-commercial robotic deployments and unverified prototype-stage orchestration platforms lacking enterprise deployment history.
Recent Developments, Partnerships, and Product Launches
Recent industry momentum is characterized by strategic partnerships between pure-play software firms like InOrbit Inc. and hardware makers like Mobile Industrial Robots (MiR) A/S. These alliances aim to streamline out-of-the-box integration for complex manufacturing and retail environments.